Effective Strategies for Establishing Financial Reserves in the UK
Understanding the Savings Landscape of UK Households

It is essential for British households to evaluate their income stability and spending patterns. This analysis helps pinpoint weaknesses in financial preparedness, particularly against economic downturns. Numerous families encounter income variations that hinder their ability to maintain consistent savings. By examining these factors, individuals can adopt targeted strategies designed to enhance their financial well-being and readiness for potential crises.
Families should dissect their spending habits and prioritise necessary expenses. This approach enables a clearer identification of possible savings, allowing households to channel more resources into financial reserves. Conducting regular assessments of current savings equips individuals with the insights needed to make necessary adjustments, ensuring preparedness for unexpected financial hurdles.
Why Is It Vital to Establish an Emergency Fund?
Setting up a dedicated emergency fund is a crucial step towards achieving financial resilience. This fund is intended to cover unforeseen expenses, such as car repairs or job losses, which are frequent occurrences in the UK. By committing to save a specific sum each month, individuals can steadily build a safety net that guarantees long-term security and peace of mind.
An effective emergency fund typically includes three to six months’ worth of essential living expenses. This buffer is invaluable during periods of financial instability. It is essential to keep these funds easily accessible but separate from everyday spending accounts to avoid the temptation to use savings for non-emergency purposes.
Which Government Assistance Schemes Can Enhance Financial Stability?
The UK government provides various support schemes, including Universal Credit, Jobseeker’s Allowance, and housing benefits, offering additional layers of financial protection during crises. Exploring these resources allows residents to maximise their entitlements and ensure they receive crucial support during economic hardships.
Staying informed about updates to government support schemes is vital, as eligibility criteria and available assistance can change. A solid understanding of these resources empowers individuals to navigate challenging times more effectively, enhancing their financial stability and enabling informed decision-making regarding personal finances.
In What Ways Can Budgeting Techniques Improve Savings?
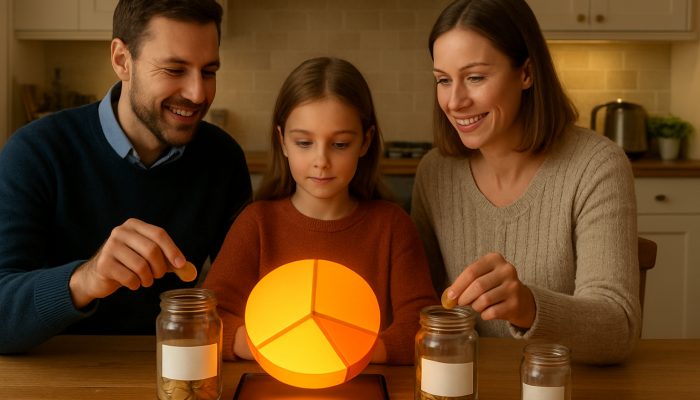
Implementing effective budgeting techniques is crucial for British families seeking to build substantial financial reserves. Various methods, such as the 50/30/20 rule, assist individuals in allocating their monthly income toward savings, essential expenses, and discretionary spending. This strategy encourages consistent savings contributions, improving readiness for unforeseen financial challenges.
Regularly reviewing and adjusting budgets is essential to ensure alignment with changing financial goals. By utilising budgeting tools and applications, individuals can gain insights into their spending behaviours and identify areas for improvement, ultimately fostering enhanced economic security amid fluctuating circumstances.
Why Is It Important to Evaluate Insurance Options for Financial Protection?
Assessing different insurance options is a fundamental aspect of protecting accumulated reserves against potential losses. UK residents should consider various policies, including health insurance, home insurance, and income protection insurance, to ensure comprehensive coverage. These measures can help mitigate the financial impact of accidents, illnesses, or property damage.
Investing in robust insurance policies not only safeguards personal assets but also provides peace of mind. By understanding the various insurance products available, residents can make informed decisions that align with their financial goals, guaranteeing sustained stability over time.
Professional Insights on Creating Financial Buffers for Future Economic Resilience
Showcasing Successful Community Initiatives Across the UK
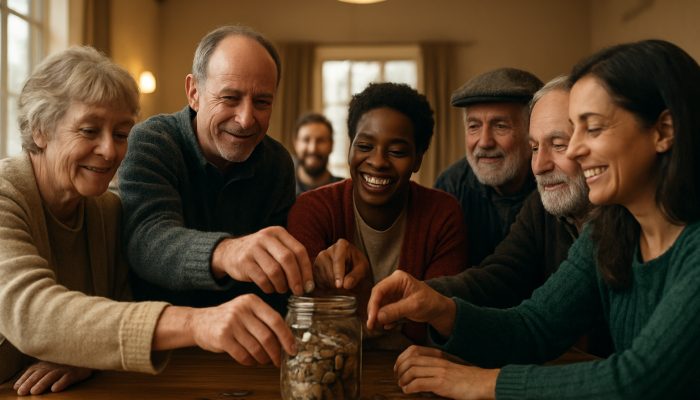
Local initiatives throughout the UK have effectively mitigated the effects of recent economic events through community-driven savings groups. For instance, credit unions in Wales and Scotland have provided essential financial services, enabling members to save collectively and access low-interest loans during challenging times.
These community efforts have strengthened resilience among participants, demonstrating the power of collaboration. By pooling resources and sharing knowledge, individuals can create more substantial financial buffers, ensuring they are better prepared to face future economic shocks.
How Can Policy Revisions Enhance Economic Resilience?
Recent changes to fiscal policies in the UK have paved the way for improved support structures. For example, alterations to tax relief for savings and investments can motivate individuals to enhance their financial reserves more effectively. Being aware of these policy adjustments allows residents to modify their strategies and take advantage of new regulations.
By remaining informed about governmental changes, individuals can navigate the financial landscape with greater skill. This adaptability is vital for increasing personal stability and resilience, particularly in a rapidly evolving economic environment.
What Practical Steps Can Facilitate Effective Implementation?
To effectively build financial buffers, UK residents should consider implementing actionable strategies tailored to their specific circumstances. Start by developing a comprehensive budget, identifying areas where savings can be maximised, and setting concrete savings objectives. This structured approach enables individuals to consistently allocate funds to their financial reserves.
Automating savings transfers can streamline the process. By establishing direct debits to a designated savings account, individuals can prioritise saving each month. This disciplined approach fosters a habit of saving, ultimately leading to improved financial security.
Why Is Diversification Essential for Achieving Financial Security?
Diversifying investment portfolios is crucial for creating strong buffers against unexpected economic disruptions. Leading financial analysts in the UK emphasise the importance of including a range of assets, such as stocks, bonds, and real estate, to reduce risk and enhance overall returns. This strategy not only protects against market fluctuations but also opens avenues for growth.
By distributing investments across various sectors, individuals can safeguard their financial reserves. This diversification enables residents to better withstand economic turbulence, ensuring long-term financial stability and security in an unpredictable world.
How Can Technological Advancements Support the Creation of Financial Buffers?
Modern financial technology applications are revolutionising the way individuals manage their finances in the UK. These innovative tools allow users to automate regular savings transfers, track spending habits, and even set financial goals. By harnessing technology, individuals can strengthen their resilience against potential future economic shocks through disciplined financial management.
Utilising applications that monitor expenses and provide insights into spending patterns empowers users to make informed decisions. This proactive approach fosters a culture of saving and financial responsibility, ultimately contributing to stronger financial buffers.
Efficient Management of Resource Allocation
Identifying Vulnerabilities in Supply Chain Dependencies
Analysing dependencies on imports and domestic production in the UK reveals areas that require diversification to prevent disruptions during supply shortages. Recent events, such as the COVID-19 pandemic, have underscored the necessity of recognising these vulnerabilities, prompting both businesses and households to reassess their resource allocation strategies.
By identifying critical supply chain weaknesses, individuals and organisations can devise contingency plans. This proactive approach ensures preparedness for potential disruptions, safeguarding financial stability and access to essential goods and services.
What Strategies Support Sustainable Stockpiling?
Creating plans for the storage of essential goods is crucial for British households seeking to maintain access during uncertain times. Focusing on non-perishable items like canned goods, dried foods, and toiletries ensures families are well-prepared for unexpected challenges, ranging from natural disasters to economic downturns.
To stockpiling non-perishables, households should consider implementing a rotation system to manage their supplies effectively. This method minimises waste and guarantees that items remain fresh and usable. Through strategic planning, families can bolster their resilience and readiness for future shocks.
How Can Technology Enhance Effective Resource Monitoring?
Utilising digital tools available in the UK allows for real-time tracking of resource levels, supporting proactive adjustments to buffer systems. Numerous applications and platforms enable households to monitor their inventories, ensuring awareness of available resources and optimal times to replenish supplies.
By integrating technology into resource management, individuals can make informed decisions regarding their needs. This proactive methodology cultivates a culture of preparedness, ensuring families are well-equipped to navigate uncertainties and maintain stability in challenging times.
Research-Backed Advantages of Establishing Financial Buffers for Future Resilience
Examining Economic Data from Recent Challenges
Analysing reports on UK recessions illustrates how pre-existing buffers significantly alleviated financial pressure for numerous families and businesses. Data indicates that households with established emergency funds were able to navigate economic downturns more effectively, enabling them to weather financial storms without resorting to high-interest debt.
These findings highlight the importance of proactive financial planning. By building buffers, individuals can enhance their resilience and better prepare for future economic challenges, ultimately leading to greater financial stability.
Highlighting Successful Practices from UK Industries
Sectors such as manufacturing have successfully employed buffer strategies to overcome past challenges in the UK. For instance, companies that implemented inventory management systems during economic downturns were able to maintain operations and protect jobs, showcasing the effectiveness of strategic resource allocation.
These real-world examples underscore the necessity of adopting buffer strategies across diverse industries. By learning from successful practices, businesses can create tailored approaches that enhance their resilience and ensure long-term stability in a constantly evolving market.
Exploring the Impact on Health and Wellbeing
Investigating the connection between financial security and mental health in the UK reveals the broader benefits of proactive buffer building. Research indicates that individuals with established financial reserves experience lower levels of stress and anxiety, contributing to overall well-being.
By prioritising financial stability, individuals can improve their quality of life. This holistic perspective acknowledges that building buffers not only protects against economic shocks but also fosters a healthier, more balanced lifestyle.
What Long-Term Benefits Arise from Building Financial Buffers?
Monitoring Progress Over Time
Assessing the effectiveness of financial buffers through annual reviews enables UK residents to refine their strategies based on changing personal and national circumstances. Regular evaluations help individuals identify areas for improvement and adjust their methods accordingly, ensuring ongoing relevance and effectiveness.
By setting long-term financial goals and tracking progress, individuals can remain accountable and motivated. This continuous evaluation process nurtures a culture of financial responsibility, ultimately leading to sustained stability and resilience in the face of future challenges.
How Can Strategies Adapt to Changing Economic Conditions?
Adjusting strategies in response to interest rate fluctuations is essential for maintaining the robustness of financial safeguards in the UK. As economic conditions shift, individuals must be ready to modify their budgets and investment strategies to ensure they align with their financial objectives.
By staying informed about economic trends and developments, residents can make informed decisions that strengthen their financial resilience. This adaptability is crucial for navigating the complexities of a dynamic financial landscape.
What Are the Benefits of Community Support Networks?
– Strengthened relationships among neighbours
– Enhanced resource sharing during crises
– Increased access to local knowledge and skills
– Greater emotional support during challenging times
Collaborative efforts among neighbours in the UK can significantly enhance community resilience. By sharing resources and expertise, individuals can create a supportive environment that helps everyone navigate prolonged difficulties more effectively.
How Does Financial Independence Contribute to Lasting Security?
Reflecting on sustained financial stability achieved through consistent buffering practices empowers UK residents to attain greater independence and security amid future uncertainties. By prioritising financial planning and building buffers, individuals can manage economic challenges and personal transitions with confidence.
This proactive approach not only strengthens individual resilience but also fosters a more stable and secure community. As individuals embrace financial independence, they cultivate a culture of responsibility and preparedness that benefits all.
Frequently Asked Questions
What is the purpose of building financial buffers?
Building financial buffers equips individuals for unexpected expenses or economic downturns, providing a safety net that enhances financial stability and security.
How much should I save for an emergency fund?
It is generally advisable to save three to six months’ worth of living expenses in an emergency fund to effectively cover unforeseen costs.
What government support schemes are available in the UK?
The UK provides various support schemes, including Universal Credit, Jobseeker’s Allowance, and housing benefits, to assist residents during financial difficulties.
What budgeting techniques can enhance savings?
Techniques such as the 50/30/20 rule and zero-based budgeting can help individuals effectively allocate their income, prioritising savings and essential expenses.
How can I diversify my investment portfolio?
To diversify your portfolio, consider incorporating a mix of asset classes such as stocks, bonds, and real estate, which can help mitigate risk and enhance returns.
What role does technology play in managing finances?
Technology simplifies financial management through applications that automate savings, track spending, and provide insights, assisting users in effectively building financial buffers.
How can I identify supply chain vulnerabilities?
Identifying supply chain vulnerabilities involves analysing dependencies on imports and domestic production, enabling individuals and businesses to develop diversification strategies.
What are the benefits of stockpiling essential goods?
Stockpiling essential goods ensures access during uncertainties, minimises panic buying, and allows households to maintain stability amid disruptions.
How can I monitor my resource levels effectively?
Utilising digital tools and applications can assist in tracking resource levels in real-time, enabling proactive adjustments to ensure sufficient supplies.
What are the long-term outcomes of building financial buffers?
Long-term outcomes include enhanced financial independence, improved resilience against economic shocks, and a greater sense of security and well-being.
Visit our Facebook profile today!
This article was first published on: https://www.debtconsolidationloans.co.uk
The article Buffers for Absorbing Future Shocks: Essential Tips was first found on https://electroquench.com