Establishing Clear Borrowing Guidelines for Financial Prosperity
How Can You Effectively Define Your Borrowing Objectives?

When crafting personal borrowing rules, it is vital to articulate precise objectives that align with your financial goals. In the UK, typical aspirations might include financing home renovations, addressing educational expenses, or consolidating existing debts. By specifying these objectives, you ensure that every borrowing decision contributes positively to your financial aspirations, thus avoiding unnecessary debt accumulation.
Comprehending the rationale behind your borrowing plays a crucial role in selecting the most appropriate type of loan or credit option. For example, if your aim is to fund home improvements, a secured loan may be a more suitable choice than an unsecured personal loan. This focused strategy not only aids informed decision-making but also guarantees that your borrowing is consistent with your overarching financial strategy.
Setting explicit borrowing objectives enables you to track your progress and evaluate your success. Regularly revisiting these goals ensures your borrowing remains purposeful and adaptable to changing circumstances, such as fluctuations in income or unexpected expenses. This proactive stance fosters financial stability and alleviates the stress often associated with debt management.
What Key Steps Should You Follow to Evaluate Your Income Stability?
Regularly reviewing your income is essential to ensure that your borrowing stays within your financial limits. The Financial Conduct Authority (FCA) in the UK advises consumers to conduct a thorough assessment of their financial situations before taking on debt. This evaluation includes analysing your monthly income and expenditures to establish a realistic borrowing capacity.
When evaluating income stability, consider factors such as job security, potential promotions, and any changes in employment status. For instance, if you are self-employed or work on a zero-hours contract, your income may fluctuate considerably, affecting your ability to repay loans. Recognising these nuances helps you set borrowing limits that truly reflect your financial capabilities.
Creating a budget that considers both fixed and variable expenses provides clarity on how much you can comfortably borrow. This budgeting exercise not only aids in defining borrowing limits but also encourages disciplined financial management, ensuring you remain within your means while pursuing your financial objectives.
How Can You Establish Your Maximum Loan Amounts?
Determining a maximum loan amount is a critical component of formulating personal borrowing guidelines. It helps prevent financial overextension and supports the maintenance of a robust credit profile. Here are several benefits of setting maximum loan amounts:
- Averts excessive borrowing and the stress that often accompanies it.
- Fosters disciplined financial habits.
- Supports the maintenance of a healthy credit score.
- Ensures that repayments remain within manageable limits.
- Enhances financial planning.
By identifying a maximum loan amount, you establish a safety net that safeguards your financial well-being. This practice encourages you to assess whether the debt is genuinely necessary and advantageous to your overall financial situation. It also instils a sense of responsibility, as you commit to operating within defined boundaries.
Regularly reassessing your maximum loan amounts is vital, particularly as your financial circumstances evolve. Changes in income, expenditures, or life events may necessitate adjustments to these limits, ensuring they remain relevant and practical over time.
How Can You Thoroughly Evaluate Your Financial Situation?
Why Is It Crucial to Review Your Current Debts?
Before considering additional borrowing options, compiling a thorough list of your existing debts is essential. This list should include credit cards, personal loans, and other financial commitments. Understanding your total liabilities is critical for making informed borrowing decisions in the UK.
Calculating your total obligations enables you to evaluate how much additional debt you can realistically manage. This assessment is particularly relevant in light of the FCA’s guidelines, which advocate for responsible lending and borrowing practices. Being aware of your current debt levels helps you avoid taking on more than you can handle, thereby minimising the risk of entering a cycle of debt.
Reviewing existing debts can also reveal opportunities for consolidation or refinancing. For example, if you have high-interest credit card debt, considering a personal loan with a lower interest rate could reduce your monthly payments. This proactive strategy not only improves your financial condition but also ensures alignment with your borrowing guidelines.
What Is the Most Effective Way to Calculate Affordability Ratios?
Calculating affordability ratios is essential for determining safe borrowing levels based on your disposable income. Many financial advisors in the UK recommend utilising standard budgeting tools to accurately assess your financial health. These tools help you compare your income against your expenses, providing a clear overview of how much you can afford to borrow.
To calculate your affordability ratio, consider your total monthly income relative to your essential expenses, including rent or mortgage payments, utilities, and groceries. This calculation helps identify your disposable income available for loan repayments. A common guideline suggests that debt repayments should not exceed 30% of your disposable income, promoting sustainable borrowing practices.
Regularly updating your affordability calculations is crucial as your financial situation evolves. Factors such as salary increases, job changes, or unforeseen expenses can all influence your ability to repay loans. By closely monitoring your affordability ratios, you can adjust your borrowing rules as necessary to ensure they remain relevant and effective.
How Can You Recognise Potential Borrowing Risks?
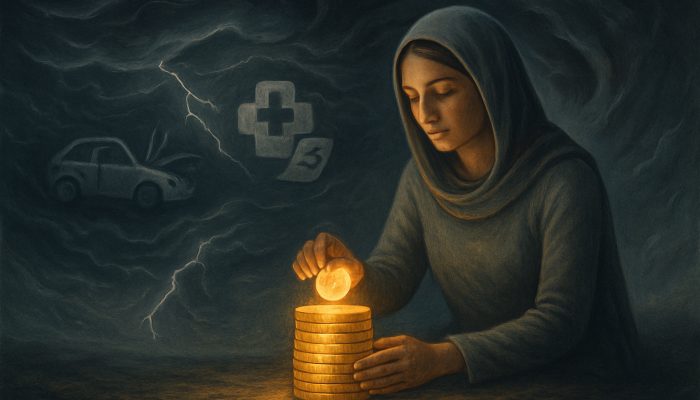
Recognising potential risks linked to borrowing is essential for managing your financial health. Unexpected expenses can arise at any moment, impacting your ability to meet repayment deadlines. In the UK, common risks include car repairs, medical emergencies, or sudden job losses. Identifying these risks early allows you to prepare and adjust your borrowing strategy accordingly.
To mitigate these risks, consider establishing an emergency fund that can cover at least three months’ worth of essential expenses. This reserve acts as a financial buffer, enabling you to manage unexpected costs without compromising your loan repayments. Prioritising this fund before taking on new debt enhances your financial resilience.
Regularly reviewing your household budget can also help pinpoint areas where you can reduce spending in anticipation of potential risks. This proactive approach not only protects your financial stability but also underscores the importance of adhering to your personal borrowing guidelines, ensuring you maintain control over your finances.
What Strategies Should You Employ for Effective Repayment Plans?
How to Choose Appropriate Loan Terms
Selecting suitable loan terms is vital for developing effective repayment plans that reflect your financial circumstances. In the UK, a variety of loan products offer different repayment periods, making it crucial to choose terms that align with your job stability and expected income growth. For instance, if you anticipate a salary increase soon, opting for a longer repayment period may ease initial financial pressure.
Consider the implications of shorter versus longer loan terms. While shorter terms usually require higher monthly payments, they can save you money on interest over the loan’s duration. Conversely, longer terms may lead to lower monthly payments but can result in higher overall interest costs. Evaluating your financial landscape helps you strike a balance that meets your needs and capabilities.
It is essential to thoroughly understand the terms and conditions associated with each loan option. Familiarise yourself with any fees, penalties, or stipulations that might affect your repayment plans. This awareness empowers you to make informed decisions and set realistic expectations for your borrowing journey.
How to Integrate Buffer Periods into Your Repayment Plans?
Incorporating buffer periods into your repayment plans is a wise strategy to account for potential delays in payments. In the UK, seasonal variations in utility bills or unforeseen expenses can impact your cash flow. By allowing extra time in your repayment schedule, you create a safety net that helps you manage these fluctuations without falling behind on payments.
When formulating your repayment plan, consider incorporating a buffer period of one or two months. This additional time can provide peace of mind, knowing that you have flexibility should financial challenges arise. It also allows you to adjust your budget accordingly, ensuring that you stay on track with your loan commitments.
Regularly reviewing your repayment schedule can help you identify potential issues before they escalate. By closely monitoring your financial situation, you can make timely adjustments to your buffer periods, ensuring they remain relevant to your circumstances and continue to support your financial stability.
How to Monitor Your Progress?
Tracking your progress against your repayment plans is crucial for maintaining control over your finances. Regularly monitoring each instalment ensures alignment with your initial plans and helps you avoid penalties from financial institutions in the UK. This proactive approach enables you to identify discrepancies early and make necessary adjustments.
Consider setting up reminders or using budgeting apps to keep track of your payments. Many consumers in the UK find these tools beneficial for staying organised and accountable. By consistently reviewing your repayment status, you can identify potential challenges and tackle them before they develop into larger issues.
Maintaining open communication with your lender is also vital. If you encounter difficulties making payments, contacting your lender may lead to potential solutions, such as restructuring your repayment plan. This transparency fosters a positive relationship with your lender and demonstrates your commitment to fulfilling your financial obligations.
Expert Advice on Formulating Personal Borrowing Guidelines
What Insights Can We Gain from Real-Life Examples of British Households?
Real-life examples provide valuable insights into how families in the UK successfully manage loans through well-defined personal guidelines. For instance, a family in Manchester might implement clear borrowing rules centred on home improvements. By establishing a budget and adhering to a maximum loan amount, they could renovate their home without straining their finances.
Another example could involve a single parent in London prioritising their children’s education costs. By crafting a detailed financial plan and adhering to personal borrowing limits, they successfully financed their children’s tuition fees while maintaining a healthy credit score. These scenarios illustrate the effectiveness of establishing personal borrowing guidelines and their positive impact on financial well-being.
These case studies highlight the importance of discipline and planning in borrowing decisions. Families that invest time in creating clear guidelines tend to experience less financial stress and greater peace of mind. By sharing these stories, others can learn from their experiences and develop borrowing strategies tailored to their unique circumstances.
What Do Experts Recommend Regarding Credit Limits?
Financial advisors in the UK often suggest capping borrowing at thirty percent of annual income to encourage sustainability. This guideline promotes manageable debt levels, reducing the risk of financial strain. By adhering to this limit, individuals can ensure they retain sufficient disposable income to cover essential expenses while meeting their repayment obligations.
Understanding the rationale behind this recommendation is essential. Limiting borrowing to a percentage of income helps prevent excess and encourages responsible financial behaviour. It also accommodates unforeseen expenses, ensuring that borrowers do not find themselves in precarious financial situations.
Financial advisors stress the importance of regularly reviewing credit limits as circumstances change. For example, if an individual’s income increases, they might adjust their borrowing limits accordingly. This flexibility fosters a proactive approach to borrowing and helps maintain a healthy financial balance.
What Practical Steps Can You Take for Regular Reviews?
Establishing actionable steps for regular reviews of your borrowing rules is vital for adapting to changing circumstances. One effective method is to conduct quarterly checks using popular online banking apps commonly used by British consumers. These apps provide a convenient way to monitor your financial health and evaluate your adherence to personal borrowing guidelines.
During these quarterly reviews, assess your income, expenses, and overall financial goals. This process enables you to identify necessary adjustments to your borrowing limits or repayment plans. Keeping a record of these reviews can help track your progress and highlight areas for improvement.
Engaging with financial planning resources, such as budgeting tools or consultations with financial advisors, can also enhance your review process. By seeking expert guidance, you can gain valuable insights into your financial situation and make informed decisions regarding your borrowing strategy.
What Measures Can You Take to Ensure Responsible Credit Utilisation?
Why Is Comparing Interest Rates Crucial?
Comparing interest rates from various providers in the UK is vital for ensuring responsible credit use. The annual percentage rate (APR) can vary significantly between lenders, and finding the most favourable terms can save you money over time. By researching options, you can identify solutions that best suit your financial situation and borrowing needs.
When comparing interest rates, consider not only the APR but also any associated fees or charges. Some lenders may offer lower rates but impose higher fees, which can affect the overall cost of borrowing. Evaluating the total cost of the loan before making a decision is essential to ensure you are making a financially sound choice.
Utilising online comparison tools can simplify the process of identifying competitive interest rates. These platforms allow you to input your financial information and receive tailored quotes from various lenders, making it easier to discover the best options available in the market.
How Can You Avoid Impulsive Applications?
Taking a moment to pause before submitting credit applications is vital for preventing unnecessary credit searches that may lower your credit score. Impulsive applications often stem from emotional decisions rather than rational financial planning. By allowing yourself time to reflect, you can make more informed choices that align with your personal borrowing rules.
Implementing a waiting period of at least a week before applying for credit can be beneficial. This pause provides an opportunity to reassess your financial situation and ensures that the loan aligns with your objectives. It also allows time for research, enabling you to identify the best terms and conditions available.
Understanding the impact of multiple credit applications on your credit score is essential. Each application generates a hard inquiry, which can temporarily lower your score. By being selective and strategic with your applications, you can protect your credit profile while still accessing the funds you require.
Why Is Maintaining Emergency Funds Critical?
Establishing an emergency fund that covers three months of expenses is fundamental to responsible borrowing. This financial cushion enables you to handle unforeseen events without defaulting on loans. In the UK, unexpected expenses like car repairs or medical bills can arise at any time, making preparedness essential.
Prioritising the creation of an emergency fund before taking on additional debt is a wise strategy. This fund can offer peace of mind, knowing that a financial safety net is in place. It also reinforces the importance of adhering to your personal borrowing rules, ensuring that you only borrow what you can afford to repay.
To build your emergency fund, consider setting aside a small percentage of your income each month. Over time, this discipline can lead to a substantial reserve, enhancing your financial resilience and reducing the stress associated with borrowing.
How to Effectively Monitor Your Credit Reports?
Regularly reviewing your credit reports from major British credit reference agencies such as <a href="https://electroquench.com/closing-old-cards-expert-tips-to-protect-your-score/">Experian</a> or Equifax is essential for maintaining an accurate reflection of your financial responsibility. Monitoring your credit report enables you to identify inaccuracies promptly, ensuring that your credit score accurately reflects your borrowing behaviour.
When reviewing your credit report, pay close attention to any discrepancies, such as incorrect account balances or unfamiliar accounts. If you notice any errors, contact the credit reference agency to dispute the inaccuracies. Taking these steps can help safeguard your credit score and ensure that you are viewed favourably by potential lenders.
Being aware of your credit utilisation ratio is crucial. This ratio, which compares your total credit card balances to your total credit limits, can significantly impact your credit score. Keeping your utilisation below 30% is generally advised, as it demonstrates responsible credit use and can enhance your borrowing prospects.
How Can You Budget for Monthly Repayments?
Creating a comprehensive monthly budget that includes all existing and prospective credit repayments is vital for ensuring ongoing affordability. This budget allows you to confirm that your borrowing commitments remain manageable while ensuring you live within your means across the UK.
Start by listing all sources of income and fixed expenses, such as rent or mortgage payments, utilities, and groceries. Next, factor in any existing debt repayments and potential new loans. This process will help you determine how much you can comfortably allocate towards additional borrowing without overcommitting.
Regularly revisiting your budget is crucial as financial circumstances change. Adjusting your budget to reflect shifts in income or unexpected expenses ensures that you remain on track with your borrowing rules. This disciplined approach fosters a healthy financial lifestyle, promoting sustainable borrowing habits over time.
What Research-Backed Advantages Are There to Establishing Personal Borrowing Guidelines?
How Can You Alleviate Financial Stress Levels?
Studies from British universities indicate that structured borrowing rules can lead to reduced anxiety levels and improved mental health outcomes. By establishing clear guidelines for borrowing, individuals can alleviate the stress associated with financial uncertainty and cultivate a sense of control over their financial situation.
When borrowers adhere to personal rules, they are less likely to fall into a cycle of debt, which can contribute to anxiety and stress. Having a plan in place fosters confidence and allows individuals to focus on their long-term financial goals instead of perpetually worrying about current debts.
The discipline of setting personal borrowing rules encourages individuals to adopt a proactive approach to their finances. This mindset not only reduces stress but also empowers borrowers to make informed decisions that align with their financial aspirations, ultimately leading to a more stable and fulfilling financial life.
How to Improve Credit Scores Over Time?
Consistent adherence to personal borrowing limits can significantly enhance <a href=”https://www.debtconsolidationloans.co.uk/how-does-debt-consolidation-affect-credit-scores/”>credit scores</a> over time. Major credit agencies in the UK recognise responsible borrowing behaviour, and maintaining a positive repayment history is crucial for establishing a robust credit profile. By sticking to established borrowing rules, individuals can boost their creditworthiness and unlock better borrowing options in the future.
A higher credit score not only opens doors to more favourable loan terms but also provides peace of mind. Borrowers with good credit scores are often perceived as lower-risk clients by lenders, making it easier to secure loans when needed. This positive cycle reinforces the importance of maintaining personal borrowing rules to support long-term financial objectives.
Regularly monitoring credit scores and reports can also help borrowers stay on track. By being aware of their credit status, individuals can make informed decisions about their borrowing habits and adjust their strategies as necessary to ensure continual improvement.
How to Enhance Long-Term Savings?
Individuals who practise disciplined approaches to borrowing often accumulate greater wealth by avoiding interest charges on unnecessary debts. By setting personal borrowing rules, they can prioritise savings and investments over high-interest debt. This shift in focus not only strengthens financial stability but also contributes to long-term wealth accumulation.
For instance, by limiting borrowing to essential expenses and steering clear of impulse purchases, individuals can redirect funds toward savings or investment accounts. Over time, these savings can grow significantly, providing a financial cushion for future needs or aspirations, such as retirement or educational expenses.
The habit of disciplined borrowing fosters a mindset of financial responsibility. This mentality encourages individuals to seek out growth opportunities, such as investing in stocks or property, rather than relying on debt for short-term satisfaction. This approach leads to a more secure financial future.
Why Is It Important to Conduct Annual Reviews of Borrowing Agreements?
How to Identify Changes in Terms?
Conducting annual reviews of your borrowing agreements is essential for identifying any changes in terms that lenders may implement. In the UK, lenders are obligated to inform borrowers about any rate increases or fee adjustments, but it is wise to remain vigilant. Regular reviews ensure that you stay informed about your financial obligations and can make educated decisions regarding your borrowing strategy.
During these reviews, take the time to thoroughly read through your loan agreements. Look for any clauses that may have changed or any new fees that have been introduced. Understanding these terms will help you evaluate whether your current borrowing arrangements remain suitable for your financial situation.
If you notice any significant changes in your agreements, consider reaching out to your lender for clarification. Open communication can lead to potential solutions, such as renegotiating terms or exploring alternative borrowing options that better suit your requirements.
How to Adapt Your Borrowing Rules to Life Events?
Major life events, such as marriage, job changes, or the arrival of a child, often necessitate updates to your borrowing rules to ensure they remain realistic and aligned with your financial situation. In the UK, these changes can considerably affect your income and expenses, making it essential to reassess your borrowing agreements accordingly.
When facing a significant life change, evaluate your financial goals and commitments. This assessment will help you determine whether your current borrowing limits are still appropriate or if adjustments are necessary to accommodate your new circumstances. For instance, if you are expecting a child, you may need to factor in additional expenses in your budget.
Consulting with a financial advisor during these transitions can provide valuable insights and guidance. Professionals can assist you in navigating the complexities of your financial landscape, ensuring that your borrowing rules remain aligned with your evolving goals and responsibilities.
How to Ensure Continued Affordability?
Reassessing your borrowing agreements based on current outgoings is vital to prevent overextension, particularly amid rising living costs throughout the UK. Regularly reviewing your financial situation allows you to identify any changes that may impact your ability to make repayments, ensuring that your borrowing remains affordable.
Consider factors such as inflation, utility costs, and changes in your income when evaluating your financial health. By staying informed about these variables, you can make necessary adjustments to your borrowing limits and repayment plans. This proactive approach helps you avoid financial strain and maintain control over your debt.
Creating a budget that reflects your current circumstances can provide clarity on your financial commitments. By incorporating all sources of income and expenses, you can assess whether your borrowing remains sustainable. This discipline reinforces the importance of adhering to your personal borrowing rules and promotes long-term financial stability.
How to Track Regulatory Updates?
Annual reviews of your borrowing agreements also ensure awareness of changes in British financial regulations that may affect your borrowing terms. Regulatory bodies, such as the Financial Conduct Authority, frequently update guidelines to protect consumers and promote responsible lending practices. Staying informed about these changes can help you maintain compliance and avoid potential penalties.
During your annual review, dedicate time to researching any new consumer protection rules or interest rate caps imposed by authorities. Understanding these regulations can empower you to make informed decisions about your borrowing strategy and ensure your agreements remain compliant with current standards.
Engaging with financial news and resources can enhance your understanding of the regulatory landscape. By staying informed, you can proactively adjust your borrowing practices to align with evolving regulations, ensuring your financial decisions remain sound and responsible.
How to Monitor Economic Indicators?
Keeping an eye on economic indicators, such as inflation rates and decisions made by the Bank of England, is crucial for understanding how shifts in the British economy impact your loan repayments. These indicators can affect interest rates and borrowing costs, making it essential to stay informed about economic trends that may influence your financial situation.
Regularly reviewing economic news and reports can provide insights into potential changes in interest rates. For example, if inflation is rising, the Bank of England may increase interest rates to stabilise the economy. Understanding these dynamics can help you make educated decisions about your borrowing strategy and adjust your agreements as necessary.
Considering how economic shifts may impact your income and expenses is vital. If you anticipate changes in your financial situation due to economic conditions, proactively adjusting your borrowing rules can help you maintain financial stability over time.
How to Cultivate Long-Term Financial Discipline?
What Are the Benefits of Automating Payment Reminders?
Setting up notifications through widely used mobile apps in Britain is an effective way to prevent missed deadlines and associated charges. Automating payment reminders ensures that you stay on top of your loan repayments, minimising the risk of late payments that can adversely affect your credit score.
Most banking apps offer features that enable you to set reminders for upcoming payments. By utilising these tools, you can create a structured approach to managing your finances, ensuring that you never miss a payment. This discipline not only enhances your financial health but also cultivates a sense of accountability in your borrowing practices.
Consider linking your payment reminders to your budgeting app for a comprehensive view of your financial commitments. This integration allows you to monitor your overall financial situation while ensuring that you remain compliant with your personal borrowing rules.
How to Educate Family Members on Borrowing Rules?
Sharing your borrowing rules with household partners and family members is essential for ensuring that everyone understands limits and contributes to collective financial goals. In the UK, financial transparency within families can lead to better decision-making and a shared commitment to responsible borrowing practices.
When discussing borrowing rules, consider involving family members in the budgeting process. This collaboration fosters a sense of teamwork and accountability as everyone becomes aware of the financial goals and limitations. By educating your family about the importance of adhering to borrowing rules, you create a supportive environment that encourages responsible financial behaviour.
Regularly revisiting these discussions can help reinforce the importance of maintaining financial discipline. As circumstances change, such as shifts in income or expenses, engaging in open conversations about borrowing rules ensures that your family’s financial strategy remains aligned with your evolving goals.
How to Celebrate Milestones Achieved in Your Financial Journey?
Recognising milestones achieved in your borrowing journey can reinforce positive financial habits and motivate you to continue adhering to your personal rules. Acknowledging accomplishments, whether it’s paying off a loan or reaching a savings goal, can provide a sense of achievement and encourage further progress.
Consider creating a list of key benefits associated with establishing personal rules around borrowing:
- Enhanced financial stability.
- Reduced stress and anxiety related to debt.
- Improved credit scores over time.
- Greater long-term savings and wealth accumulation.
By celebrating these milestones, you not only recognise your hard work but also reinforce the value of maintaining discipline in your borrowing practices. This positive reinforcement can create a cycle of success, motivating you to stay committed to your financial goals.
When Should You Consider Seeking Professional Advice?
How to Locate and Consult Independent Advisors?
Engaging certified debt counsellors approved by British regulatory bodies can provide tailored guidance on complex borrowing situations. These professionals possess the expertise to help you navigate the intricacies of borrowing and ensure that your personal rules align with your financial goals.
When seeking advice, look for independent advisors who prioritise your best interests. They can assess your financial situation, identify potential risks, and recommend strategies for responsible borrowing. This tailored guidance empowers you to make informed decisions and enhance your financial stability.
Consider scheduling regular check-ins with your advisor to discuss any changes in your financial situation. This proactive approach allows you to adjust your borrowing rules as needed and ensures that you remain aligned with your long-term goals.
How Can You Utilise Free Financial Resources?
Accessing government-backed websites offering impartial information on borrowing rights and responsibilities in Britain can significantly enhance your understanding of personal finance. These resources provide valuable insights into consumer protections, lending regulations, and best practices for responsible borrowing.
Utilising these free resources allows you to educate yourself about your rights as a borrower. Understanding the legal framework surrounding borrowing empowers you to make informed decisions and advocate for yourself when necessary. This knowledge fosters confidence in your borrowing practices.
Engaging with community resources, such as local financial workshops or seminars, can further enhance your understanding of responsible borrowing. These opportunities provide a platform for learning and sharing experiences with others, promoting a culture of financial literacy within your community.
How to Join Support Communities for Borrowing Discipline?
Participating in local forums where individuals discuss strategies for maintaining personal borrowing discipline can offer valuable insights and support. These communities provide a space for sharing experiences, challenges, and successes related to borrowing, fostering camaraderie among members.
Joining support communities can also grant access to a wealth of knowledge and resources. Members often share tips, tools, and strategies that have proven effective for them, allowing you to learn from their experiences. This collaborative approach can enhance your understanding of responsible borrowing and motivate you to remain committed to your personal rules.
Engaging with others who share similar financial goals can create accountability. Discussing your progress and challenges with fellow community members reinforces your commitment to maintaining discipline in your borrowing practices, ultimately leading to improved financial outcomes.
Frequently Asked Questions
What constitutes personal rules around borrowing?
Personal rules around borrowing are guidelines that individuals create to manage their borrowing behaviours responsibly. These rules help define borrowing limits, repayment plans, and financial goals, ensuring that borrowing remains manageable and sustainable.
Why is it crucial to set borrowing limits?
Establishing borrowing limits is vital to prevent overindulgence and maintain financial stability. By creating clear guidelines, individuals can avoid excessive debt and ensure their borrowing aligns with their income and expenses.
How can I assess my income stability?
To evaluate income stability, review your monthly earnings and consider factors such as job security and potential changes in employment status. Regularly assessing your income helps determine how much you can afford to borrow responsibly.
What should my budget include?
Your budget should encompass all sources of income, fixed expenses (like rent and utilities), variable expenses (like groceries), and any existing or potential debt repayments. This comprehensive view helps you assess your financial health and borrowing capacity.
How often should I review my borrowing agreements?
It is advisable to review your borrowing agreements annually. This review enables you to identify any changes in terms, assess your financial situation, and ensure that your borrowing remains affordable and compliant with regulations.
What advantages does maintaining an emergency fund provide?
An emergency fund offers a financial cushion to manage unforeseen expenses without jeopardising loan repayments. It enhances your financial resilience and reduces stress associated with borrowing.
How can I improve my credit score?
Enhancing your credit score involves consistently adhering to personal borrowing limits, making timely repayments, and monitoring your credit report for inaccuracies. Responsible borrowing behaviour leads to a positive credit history.
What steps can I take to avoid impulse borrowing?
To prevent impulse borrowing, implement a waiting period before applying for credit. This pause allows you to reassess your financial situation and ensures that any borrowing aligns with your long-term objectives.
Why is it essential to seek professional advice?
Seeking professional advice from certified debt counsellors can provide tailored guidance on complex borrowing situations. Advisors help you navigate financial challenges and ensure that your personal rules align with your goals.
How can I track economic indicators affecting my borrowing?
You can monitor economic indicators by following financial news, subscribing to economic reports, and keeping an eye on decisions made by the Bank of England. Staying informed helps you adjust your borrowing strategy in response to economic changes.
Visit Our Facebook Profile!
This Article Was First Found On: https://www.debtconsolidationloans.co.uk
The Article Personal Rules for Borrowing: Effective Strategies to Consider found first on https://electroquench.com